 Give – Teach – Sell
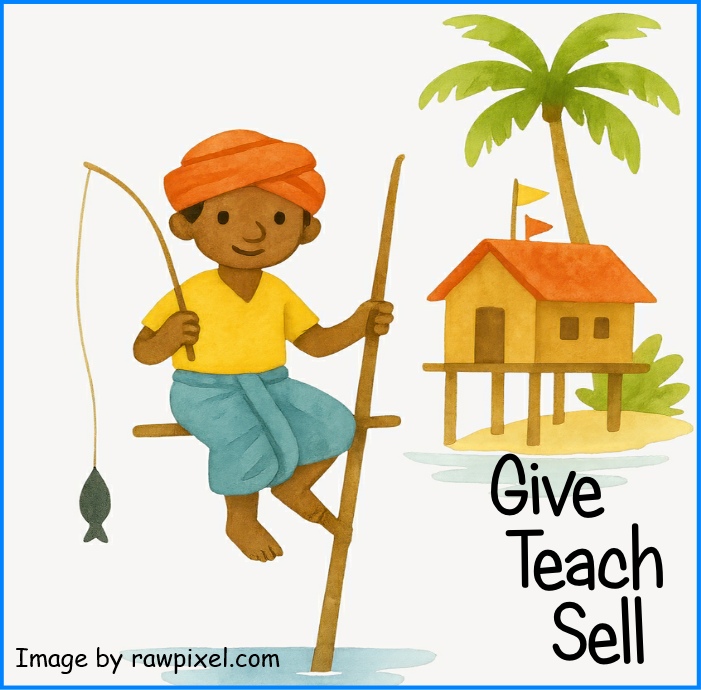
Give a man a fish and you feed him for a day.
Teach a man to fish and you feed him for life.
That well-known adage is often regarded as a fundamental premise of good charitable objects.
But doesn’t usually include a third option: “Sell a man his fish and YOU make a profit for life” – as in:
Buy up the fishing rights of the area where that man could have fished; push the man out; turn the area into a fish farm; and sell the fish (at a profit for YOURself) to the man who otherwise could have fished there for HIMself.
“Ah !...” – I hear you say – “…isn’t that the way that a good market economy should work?”
“Yes !...“ – I reply – “…when that ‘ market economy’ is functioning for the public benefit.”
But NOT when the “market” is turned into a “closed shop” where a select group of “fishing experts” connive to develop a culture of legalistic jargon and ambiguity intended to create the impression that “fishing” is too complicated for the hoi-polloi to understand and learn to “fish” for themselves. ie: they should only buy “fish” from “professionals”.
Or to put that more bluntly: such professional ”support” is NOT about creating client independence and self-sufficiency.
At best, it inadvertently creates a sense of professional superiority and client inadequacy and dependency!
At worst it’s about creating and exploiting client reliance on the professional –the primary “objective” being to create wealth for the professional!
For the charity sector, a common area of concern is unnecessarily obfuscational financial reporting rules, driving trustees’ into “reliance” on professional accountants to advise on – and, where necessary, independently examine or audit – their charity’s annual accounts.
It’s not widely recognised that most professional accountancy qualifications include only a superficial overview of charity accounting rules and regulations. ie: very few accountants are “qualified CHARITY accountants”.
In 2019 the Charity Commission expressed “concern” that its annual reviews of charity accounts consistently showed that around half were not compliant with its benchmark standards – even when signed off by a “qualified accountant”. And then abruptly stopped publishing the results of such reviews. One can only speculate why!
In 2021 I published a “Thought” on “Charity Accounts – Not Fit For Purpose” on the Small Charity Support website. One of the SORP review bodies at the time seemed to agree with me, as did the Charity Commission and the, then, CEO of the Charity Finance Group. So I was hopeful that the 2026 SORP update might make it easier for small charities to do their own annual accounts “fishing” and be less reliant on “qualified” accountants.
Alas – NO !
It seems that even the charity sector finds it difficult to escape from the power of SELL for personal profit over TEACH for public benefit.
Posted on LinkedIn on 17-Oct-26